Capital Allowances on the Construction of an AD Plant
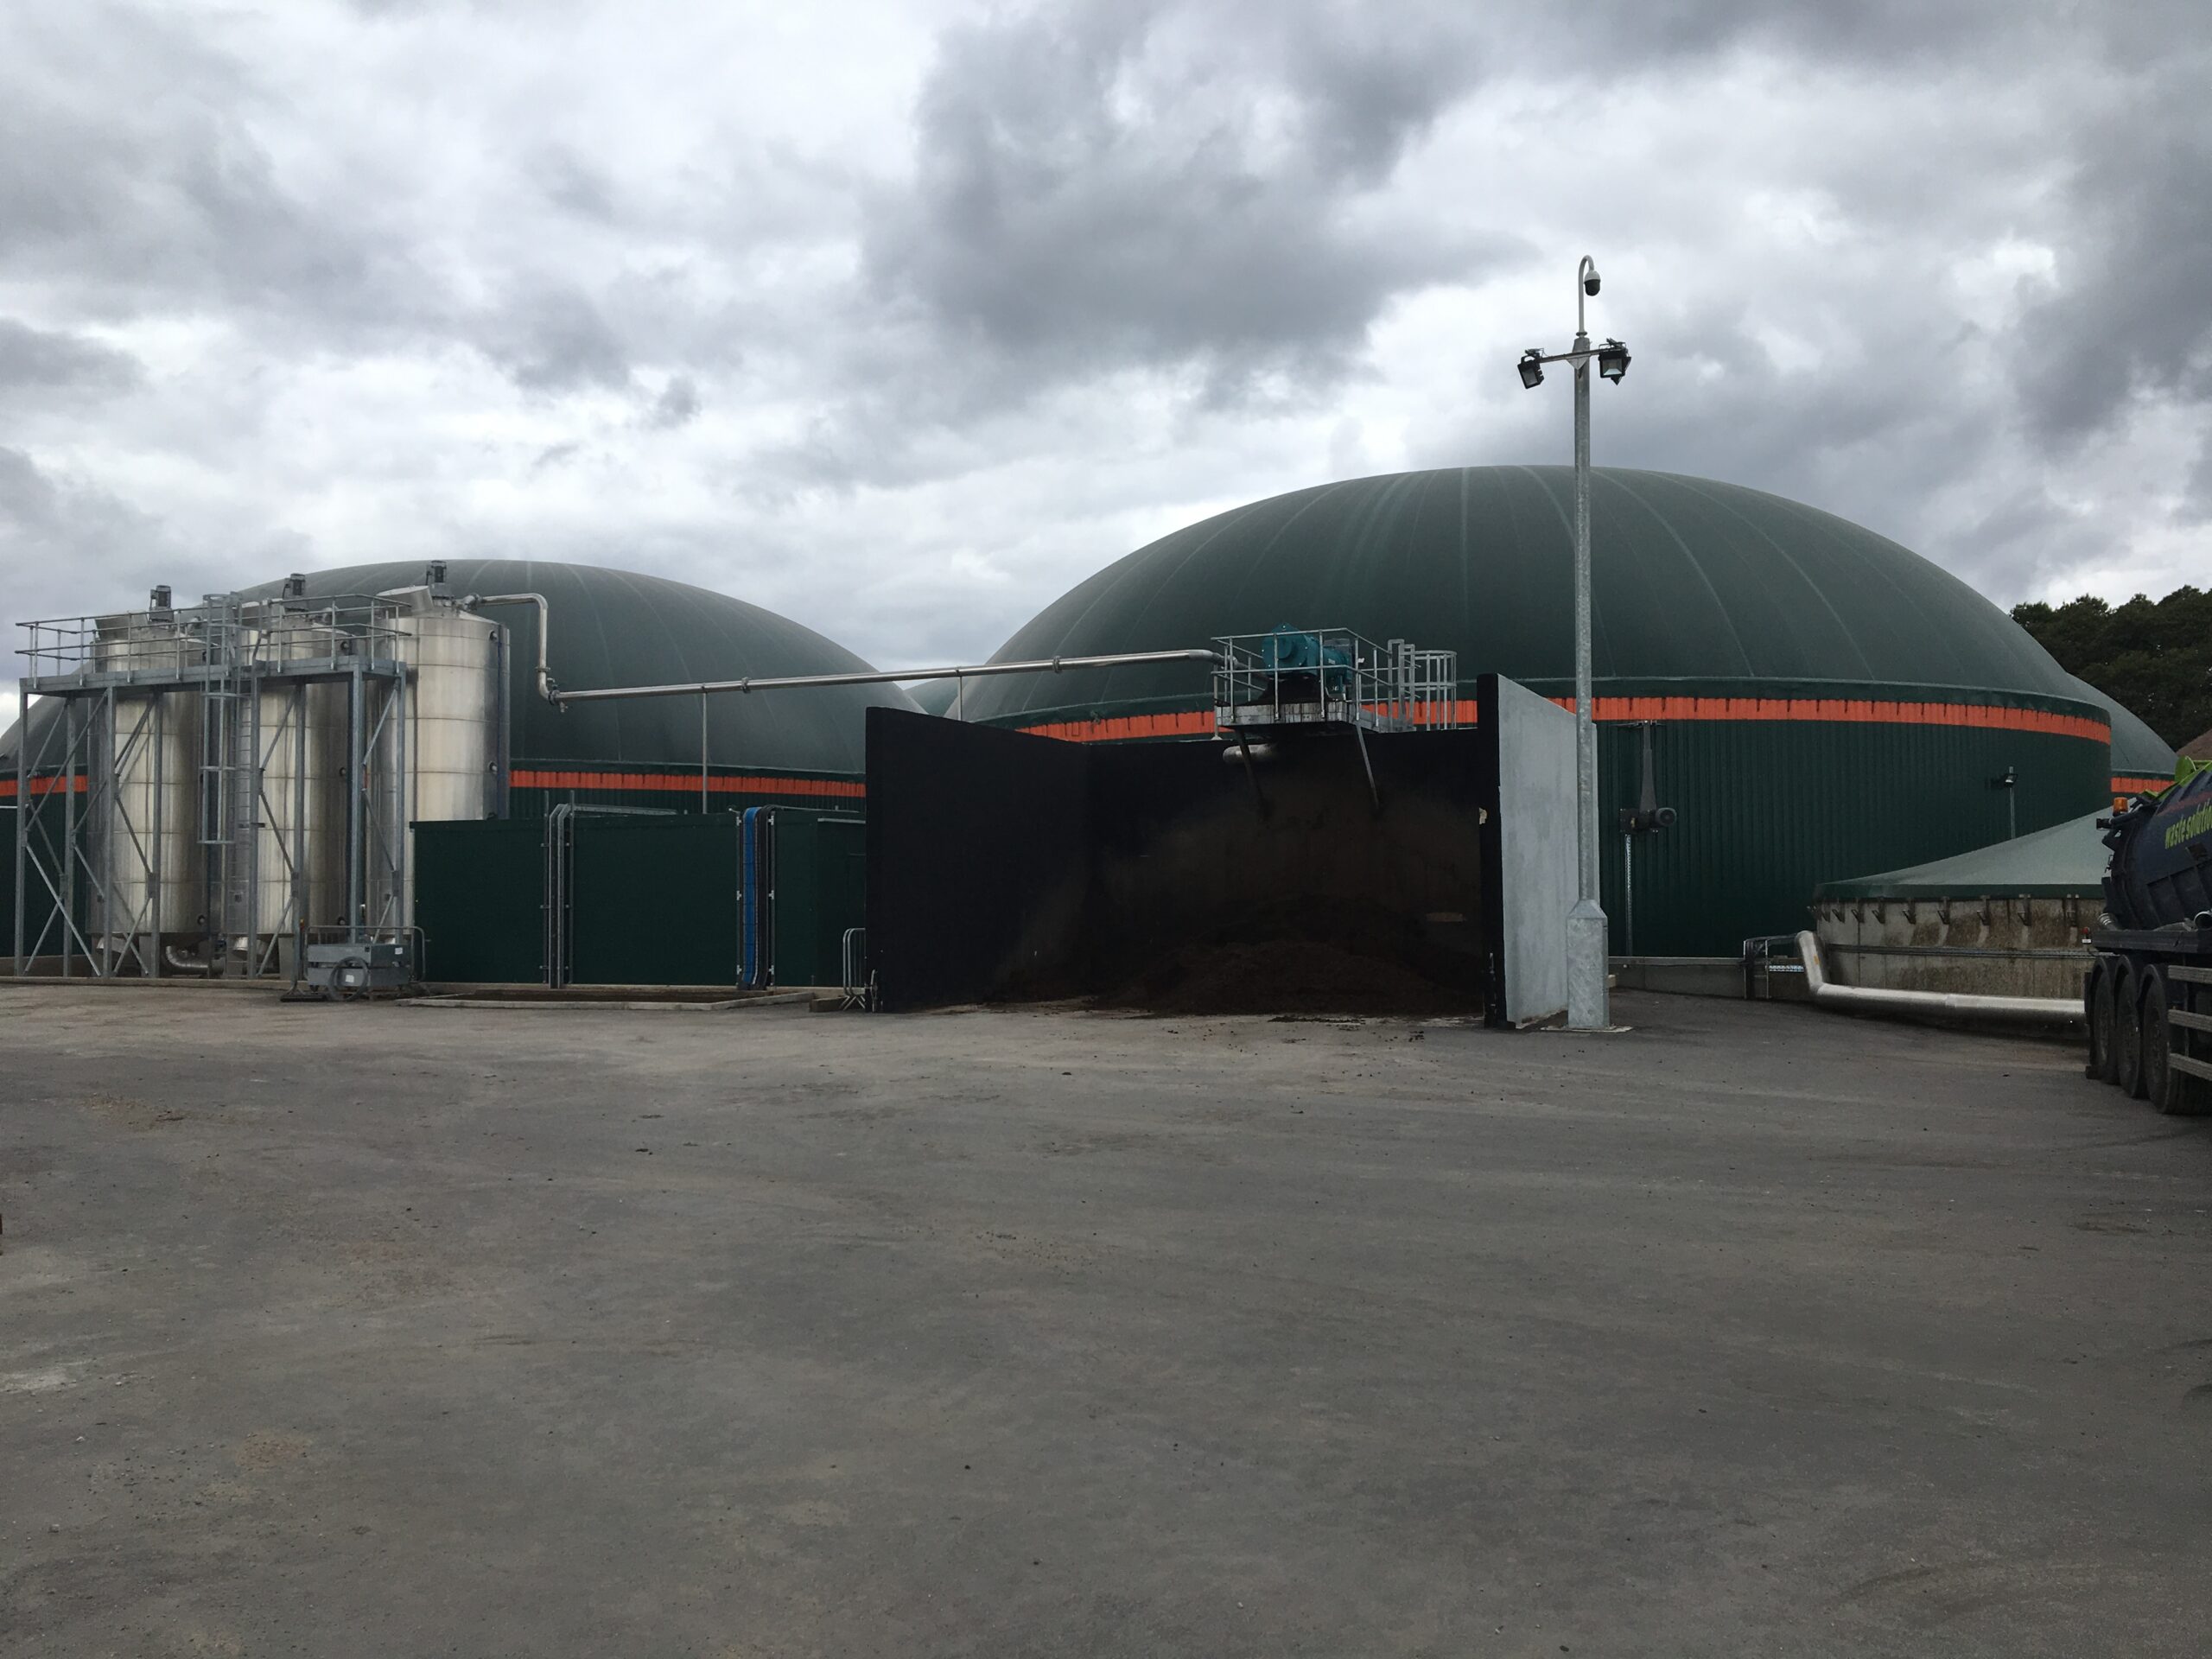
Anaerobic digestion (AD) plants continue to play an important role in the UK’s renewable energy and waste management sectors. While the construction of an AD facility often requires significant capital investment, capital allowances can provide valuable tax relief and improve the overall financial viability of a project.
A substantial proportion of expenditure incurred during the construction of an AD plant may qualify for plant and machinery allowances. Qualifying assets can include digesters, tanks, combined heat and power (CHP) units, pumps, pipework, electrical systems, control panels, feed handling equipment, and gas upgrading infrastructure.
Due to the specialist nature of AD facilities, the level of qualifying expenditure is often much higher than in conventional commercial buildings. Careful analysis of construction costs can therefore identify significant opportunities for tax relief.
The Annual Investment Allowance (AIA) may provide 100% tax relief on qualifying expenditure up to the annual threshold, allowing businesses to deduct eligible costs from taxable profits in the year the expenditure is incurred. In addition, structures and buildings allowance (SBA) relief may apply to certain construction costs that do not qualify as plant and machinery.
It is important to distinguish between qualifying operational equipment and non-qualifying structural works, as not all construction costs will attract allowances. A detailed capital allowances review can help ensure expenditure is accurately categorised and maximum relief is secured.
With the growing demand for sustainable energy solutions, capital allowances remain a key tax planning opportunity for businesses investing in AD technology and long-term renewable infrastructure.
Please get in touch with one of our directors if you would like to discuss this further.
Share This Article
This article can quickly be shared across social platforms by clicking the icons below.