UK Supreme Court clarifies scope of capital allowances for infrastructure projects
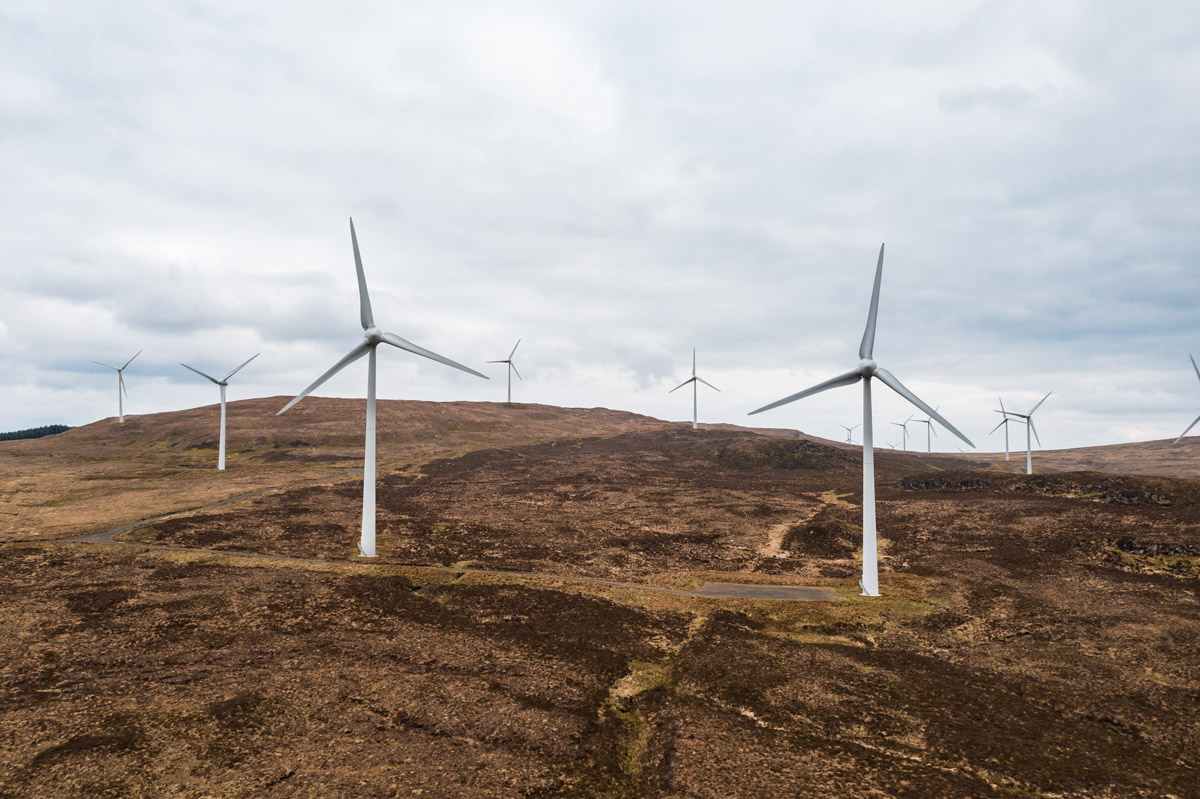
The Supreme Court has today unanimously allowed HMRC’s appeal in Orsted West of Duddon Sands v HMRC, ruling that environmental survey and feasibility study costs incurred during the planning of offshore windfarms do not qualify for capital allowances under section 11(4) of the Capital Allowances Act 2001.
While HMRC accepted that the windfarm generation assets themselves constitute “plant”, the Court held that pre-construction surveys and studies were not expenditure “on” the provision of plant, applying a deliberately narrow interpretation of the statutory wording. The Court emphasised that “on” requires a close and direct connection to the asset provided, rejecting broader concepts such as costs incurred “in connection with” or “with a view to” construction.
This decision overturns the Court of Appeal and will be highly relevant for capital intensive sectors, particularly energy, infrastructure, and large-scale development where significant upfront planning and environmental assessment costs are unavoidable.
Key Points. Not all capital, pre-construction expenditure will attract capital allowances, even where it is essential to delivering the final asset.
Full ruling can be found at https://supremecourt.uk/cases/uksc-2025-0069#judgment-details
Share This Article
This article can quickly be shared across social platforms by clicking the icons below.